A partner’s equity interest in a professional firm is often their most asset, yet it is illiquid, complex, and highly exposed to UK Inheritance Tax (IHT). Relying solely on standard Will provisions risks diluting this asset and imposing a crippling 40% tax liability on your family.
You require a specialised, integrated approach that links the firm’s Partnership Deed with robust succession and tax planning. AZL engineers this specialist framework. Our expert accountants transform your illiquid partnership asset into a tax-efficient vehicle for generational wealth transfer, guaranteeing protection and clarity for your family’s future in England and Wales.
The Financial Nature of Partnership Equity in the UK
The partnership interest differs significantly from owning shares in a limited company. Its valuation, structure, and transferability are tightly controlled, requiring precise financial definition before any planning can begin.
Defining Partnership Equity and Capital
You must distinguish clearly between a partner’s income stream and their underlying capital claim. AZL establishes the definitive basis for valuation:
Capital Account: This represents the partner’s ownership claim, typically including their initial capital contributions and any retained undistributed profits. This account forms the primary component of the asset that passes on death.
Drawings vs. Profit Share: We distinguish current Drawings (the regular income taken from the firm) from the overall Profit Share structure, ensuring tax strategies target the capital, not the income flow.
Goodwill: This is the intangible value of the business (client base, reputation). The Partnership Deed dictates how and if Goodwill is valued and accounted for upon exit or death.
The Valuation Challenge and Firm Agreements
The value used for IHT purposes may differ from the firm’s internal buy-out price. Accurate valuation is critical for both tax mitigation and ensuring a fair legacy.
Valuation Methodology: We work with your firm’s valuation methodology (Profit Share and assets) while ensuring the valuation aligns with HMRC requirements for tax purposes.
The Partnership Deed: This binding legal agreement dictates how a partner’s interest is treated upon death, often requiring the interest to be sold back to the continuing partners. AZL ensures all planning complies with these contractual restrictions.
Excepted Assets: We scrutinise the balance sheet for “excepted assets,” such as surplus cash not required for business needs, as these assets may be excluded from BPR, increasing the IHT liability.
UK Inheritance Tax (IHT) and Business Property Relief (BPR)
For UK partners, Business Property Relief (BPR) is the single most critical tax relief available. Properly securing this relief can reduce the IHT liability on your partnership interest from 40% to 0%.
Mitigating the 40% IHT Rate
UK IHT is a tax on the value of a deceased person’s estate. Without proper planning, assets exceeding the tax-free thresholds face a punitive tax rate.
Nil-Rate Band (NRB): The tax-free threshold is currently fixed at £325,000.
Residence Nil-Rate Band (RNRB): An additional £175,000 threshold is available if a main residence is passed to direct descendants, subject to tapering above a £2 million estate value.
Transferable Allowances:AZL maximises your estate’s total allowance by utilising the ability to transfer unused NRB and RNRB from a deceased spouse or civil partner, potentially securing up to £1 millions of tax-free allowance.
Securing 100% Business Property Relief (BPR)
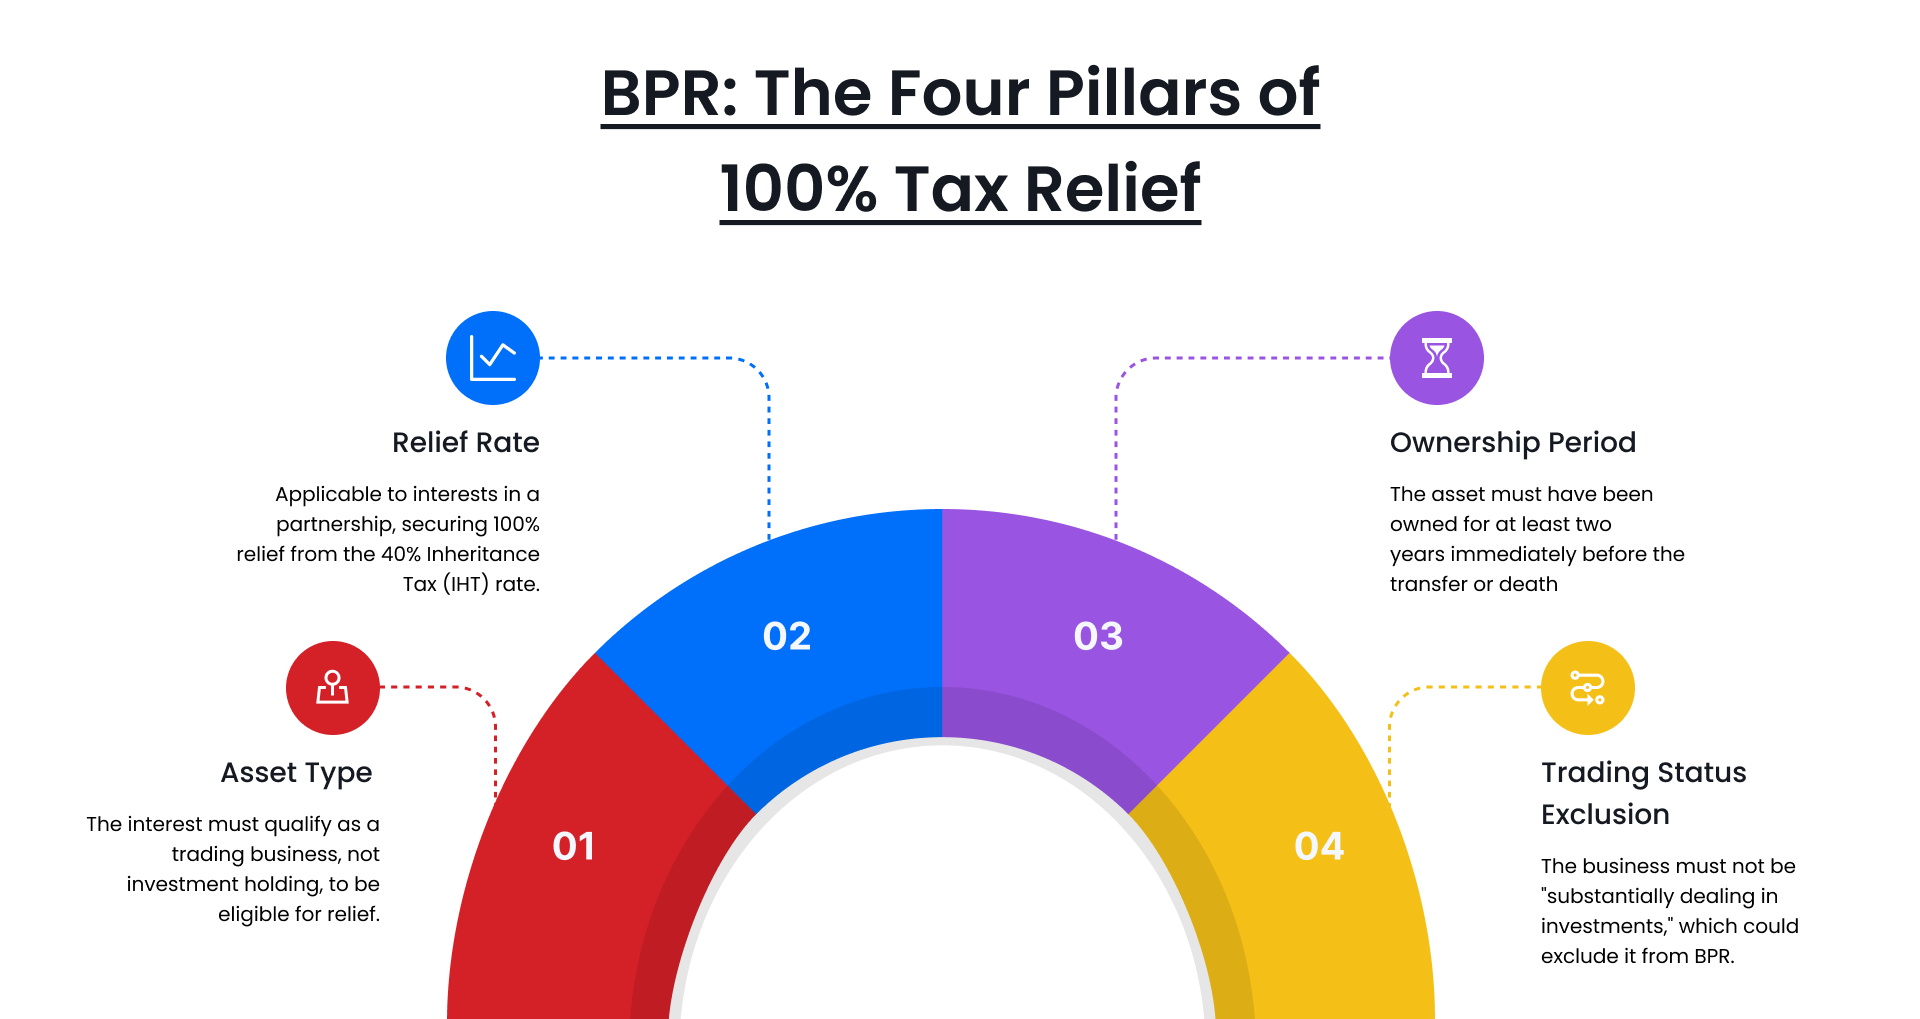
BPR allows business owners to pass on certain business assets with reduced or zero IHT liability. AZL certifies your partnership interest qualifies for the full 100% relief by verifying these crucial criteria:
BPR Qualification Condition
Required Status
AZL Compliance Verification
Asset Type
Interest in a partnership (a trading business)
Must qualify as a trading business, not investment holding.
Relief Rate
100% Relief
Applicable to interests in partnership.
Ownership Period
Owned for at least two years immediately before transfer or death.
We verify that the holding period is satisfied.
Trading Status Exclusion
Must not be “substantially dealing in investments.”
We scrutinise the firm’s activities to secure its trading status against the HMRC challenge.
Strategic Methods for Transferring Partnership Wealth
Once BPR is secured, you can employ strategic methods to transfer the underlying value of your Equity to the next generation in a tax-efficient manner, often deferring to Capital Gains Tax (CGT).
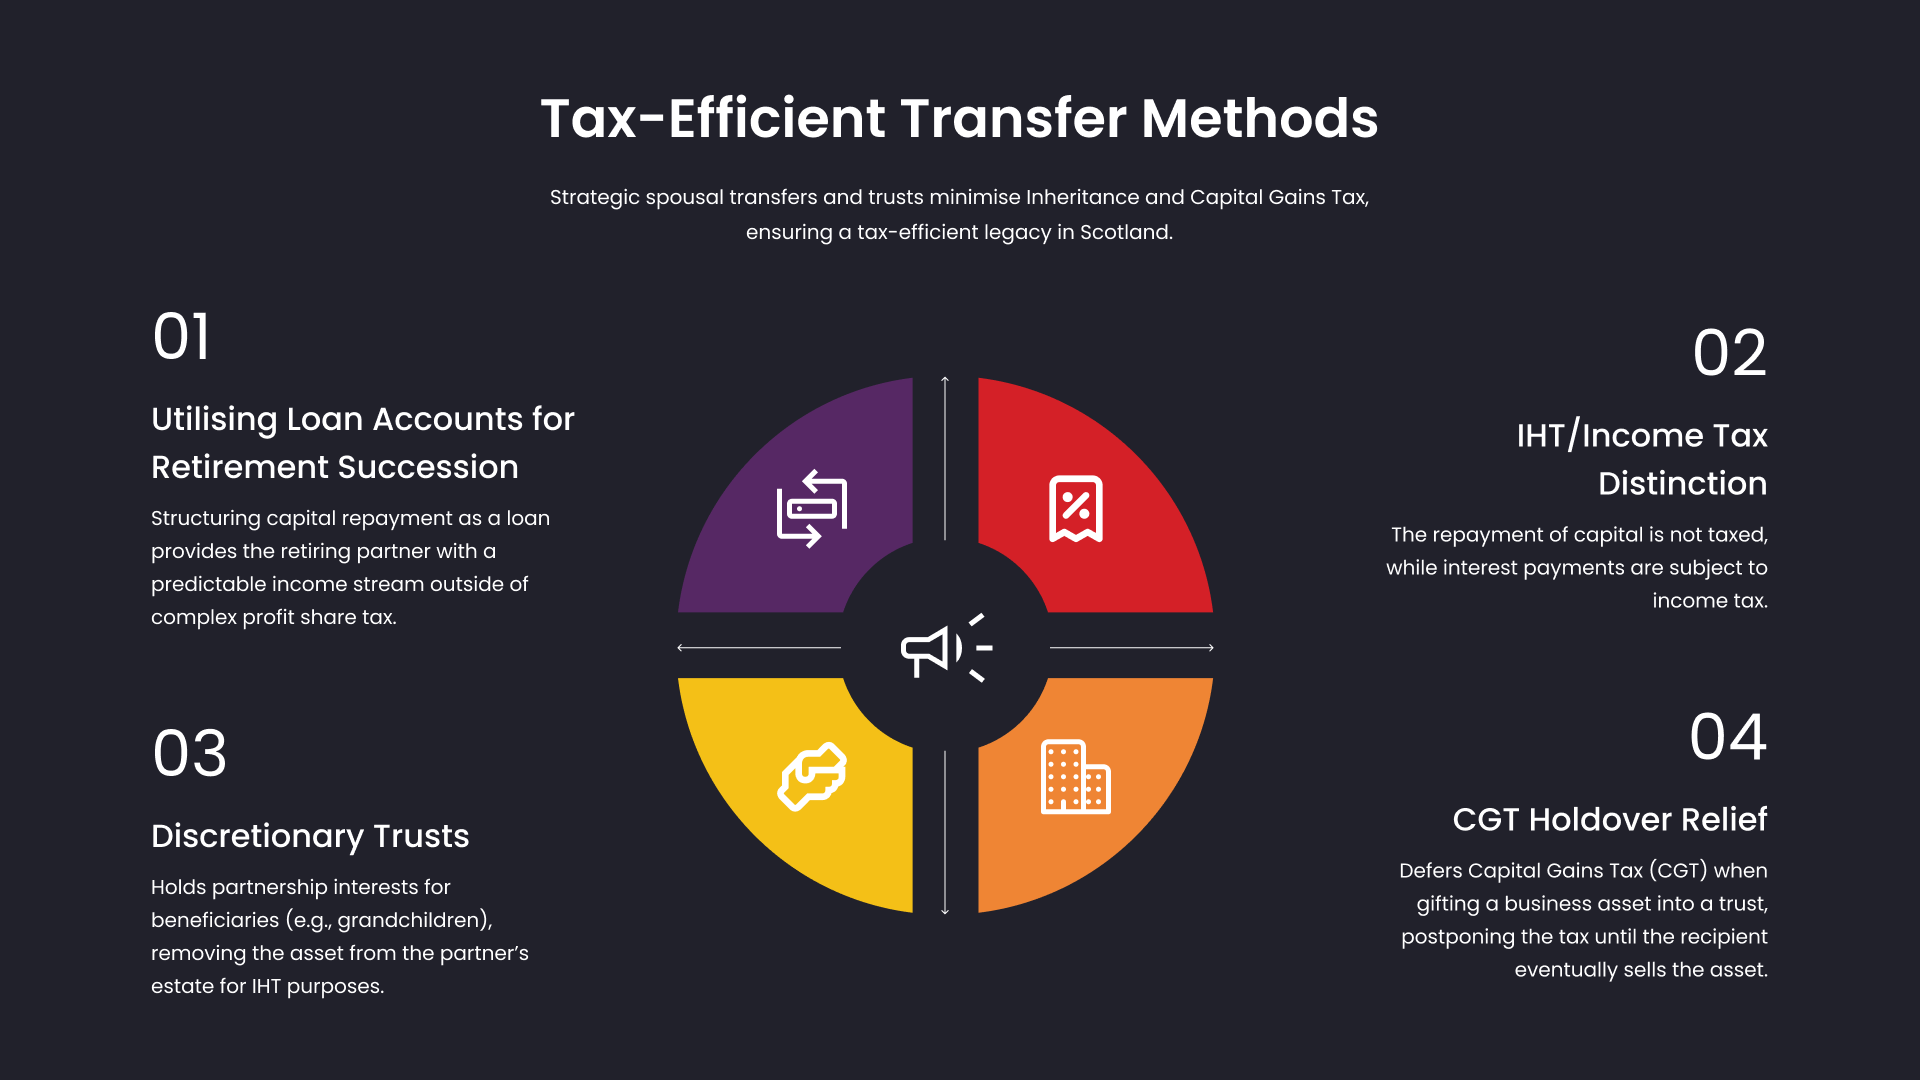
Utilising Loan Accounts for Retirement Succession
When a partner retires, the firm typically repays their Capital Account and Goodwill over a fixed period. This is often structured as a loan account.
Capital Repayment Structure: We strategically structure the partner’s retirement as a Capital Repayment via a fixed schedule (a loan account). This provides the retiring partner with a predictable income stream outside of the tax complexities of Profit Share.
IHT/Income Tax Distinction: We clarify the tax implications of the income received: loan interest payments are subject to income tax, whereas the repayment of the capital itself is not subject to tax.
Trusts and Inter-Generational Capital Transfers
Trusts are powerful legal arrangements for holding assets for beneficiaries, providing control and significant tax advantages.
Discretionary Trusts: We structure Discretionary Trusts to hold partnership interests or capital for children or grandchildren. This removes the asset from the partner’s estate immediately for IHT purposes (subject to the seven-year rule).
CGT Holdover Relief: When gifting a business asset (like a partnership interest) into a trust, Capital Gains Tax (CGT) would normally be payable. AZL executes CGT Holdover Relief to defer the gain, reducing the recipient’s base cost and postponing the tax until they eventually sell the asset.
AZL’s Expertise: Securing Your Family’s Financial Legacy
Your partnership interest requires accountancy expertise that transcends simple tax filing. AZL integrates your firm’s commercial requirements with your family’s long-term financial security.
Integrating Partnership Finances with Personal Wealth
AZL provides the critical link between the firm’s financial structure and your personal estate planning:
Optimal Profit Share Analysis: We analyse partnership Drawings and Profit Share for optimal balancing of personal income tax liability with efficient IHT planning.
Deed Compliance: We ensure all wealth structures proposed (Trusts, loan accounts) comply precisely with the specific terms of the Partnership Deed and relevant UK law.
Excepted Assets Review: We conduct a thorough review to remove any non-qualifying investments from the partnership to maximise BPR entitlement.
Securing Your Future with AZL Tax and Finance Experts
AZL guarantees specialised, up-to-date knowledge in UK wealth transfer and partnership finance.
Tax Relief Guarantee: We execute the correct application of complex reliefs, including 100% BPR and available CGT Holdover Relief.
Visual Reporting: We provide clear, concise reporting that visualises the IHT mitigation strategy, showing the tangible tax savings achieved.
Confidential Consultation: We invite you to initiate a private consultation to secure a comprehensive partnership succession plan designed entirely for the continuity of your family’s financial legacy.
Contact AZL today and convert your illiquid partnership interest into a protected, tax-efficient legacy.
Law firm partners and practice managers across England and Wales face constant regulatory pressure. Managing Value Added Tax (VAT) correctly, especially regarding client fees and the accurate definition of a disbursement presents a major financial and regulatory exposure. Misclassification on an invoice...
Unidentified funds entering your legal firm’s accounts create an immediate regulatory and financial risk. In the highly regulated environment of England and Wales, where Solicitors Regulation Authority (SRA) Accounts Rules govern every transaction, a simple bank receipt with an unknown source can jeopardise your Trial Balance and compliance standing. Law firms require an...
For law firm partners and practice managers in England and Wales, managing client finances securely and compliantly presents a persistent, high-stakes challenge. The integrity of your firm hinges on impeccable financial record-keeping. You need clarity and confidence in every transaction, ensuring you satisfy the rigorous demands of the Solicitors Regulation Authority (SRA) while maintaining profitable operations. AZL Accountants provides the specialist expertise your firm needs....


 3 July 2026
 1 July 2026