Law firm partners and practice managers across England and Wales face constant regulatory pressure. Managing Value Added Tax (VAT) correctly, especially regarding client fees and the accurate definition of a disbursement presents a major financial and regulatory exposure. Misclassification on an invoice is not a simple slip; it risks substantial HMRC penalties, significant interest charges, and costly client disputes.
Your practice demands absolute accuracy in billing to preserve its financial health. AZL Accountants provides the specialist financial and compliance guidance necessary to ensure your processes align perfectly with UK tax law. We secure your firm’s financial integrity, allowing you to focus on delivering exceptional legal service.
The Financial Framework: Core VAT Definitions for Legal Practice
Gaining absolute clarity on the fundamental structure of VAT is the essential first measure in securing accurate billing and protecting your quarterly returns. VAT is a tax levied on most goods and services in the UK, which your firm collects on behalf of HMRC.
VAT Registration: When Law Firms Must Charge the Tax
Any business providing taxable supplies in the UK must register for VAT if its taxable turnover exceeds the statutory threshold.
The Statutory Threshold: Current Turnover Requirements in the UK
As of April 1, 2024, the mandatory threshold stands at £90,000. Once your firm registers, you transition from a consumer of VAT to a collector.
This registration makes accurate classification of your services from the moment you take on a client. Our AZL accountants guide you through this process, ensuring your systems are ready before you cross the limit.
Distinguishing Supplies: Taxable vs. Exempt Services
Law firms often provide a mixture of supplies, each subject to distinct VAT treatments. Understanding these classifications dictates your billing strategy.
Taxable Supplies: Most of your standard legal services (e.g., commercial contracts, conveyancing, litigation) are subject to Standard Rate VAT (currently 20%). You collect this tax (Output Tax) and pay it to HMRC.
Exempt Supplies: Certain services, most notably publicly funded Legal Aid work, are exempt from VAT. You must not charge VAT on these services.
Legal Jargon: Input Tax and Recovery on Exempt Work (e.g., Legal Aid)
Input Tax refers to the VAT your firm pays on its own purchases (e.g., IT equipment, professional utilities).
If your firm makes exempt supplies (like Legal Aid), your ability to recover Input Tax is restricted by the rules of partial exemption.
AZL accountants specialise in calculating partial exemption accurately. We ensure you recover the maximum permissible VAT while maintaining absolute compliance with HMRC guidelines, optimising your firm’s cash flow.
Defining the Tax Point: When VAT Becomes Payable to HMRC
The Tax Point is the precise time VAT becomes legal due to HMRC. Understanding this timing is essential for managing cash flow and liability correctly.
For most standard legal services, the Tax Point occurs on the date you issue the invoice, regardless of when the client ultimately pays (accrual basis).
For solicitors, timely and accurate VAT payment is mandatory. AZL helps set up efficient accounting systems that automatically calculate and track the Tax Point, preventing late payment penalties.
The Critical Challenge: Fees Versus Disbursements
The distinction between what constitutes your professional fee and what qualifies as a client disbursement is the source of the most common and costly VAT errors encountered by law firms. This distinction is the primary area that attracts HMRC scrutiny.
Client Fees: Standard-Rated Supply and Associated Risk
Fees represent your firm’s professional income for services performed. Since these are a Standard-Rated Supply, the risk is clear:
Risk: Failing to charge the correct 20% VAT on the full fee amount.
Consequence: This results directly in an underpayment of Output Tax to HMRC.
Solution:AZL accountants audit your fee structures to ensure you apply the correct rate to all taxable professional charges, safeguarding your compliance position immediately.
Disbursements: Classification as the Primary Audit Trigger
Disbursements are costs incurred specifically on the client’s matter (e.g., search fees, stamp duty). Their classification dictates whether your firm acts as a mere agent passing a cost through, or a principal reselling a service.
The Financial Impact of Misclassification
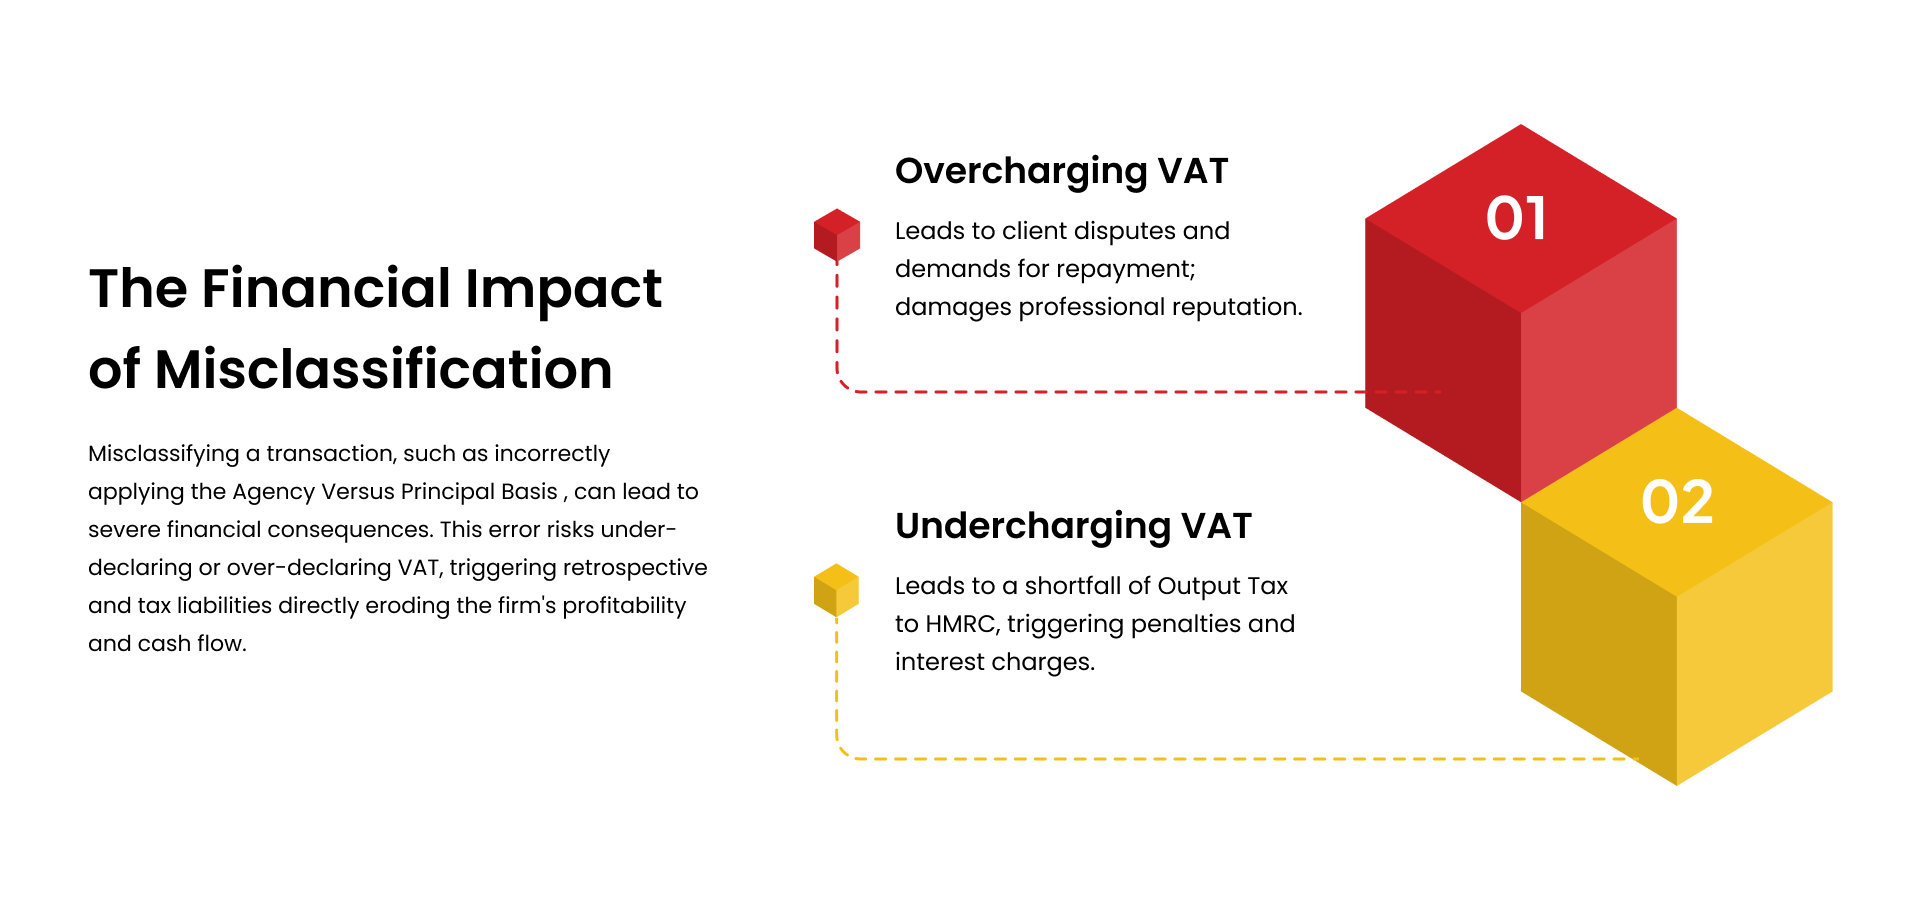
Incorrectly classifying a disbursement result in two equally serious financial outcomes. AZL Accountants helps you eliminate both:
Misclassification Type
Financial Consequence
Regulatory Risk
Overcharging VAT
Client pays VAT unnecessarily. This leads to client disputes and potential demands for repayment.
Damages client relationships and professional reputation.
Undercharging VAT
Firm fails to collect VAT that is legally due. Leads to a shortfall of Output Tax to HMRC.
Triggers HMRC penalties and interest charges on the underpaid amount.
Applying the Rules: Agency Versus Principal Basis
HMRC strictly applies to the Agency vs. Principal Rule to determine the VAT treatment of every single client at cost. Law firms must implement this mandate consistently across all fee-earners.
The Agency Basis: Costs Supplied to the Client (Non-VATable)
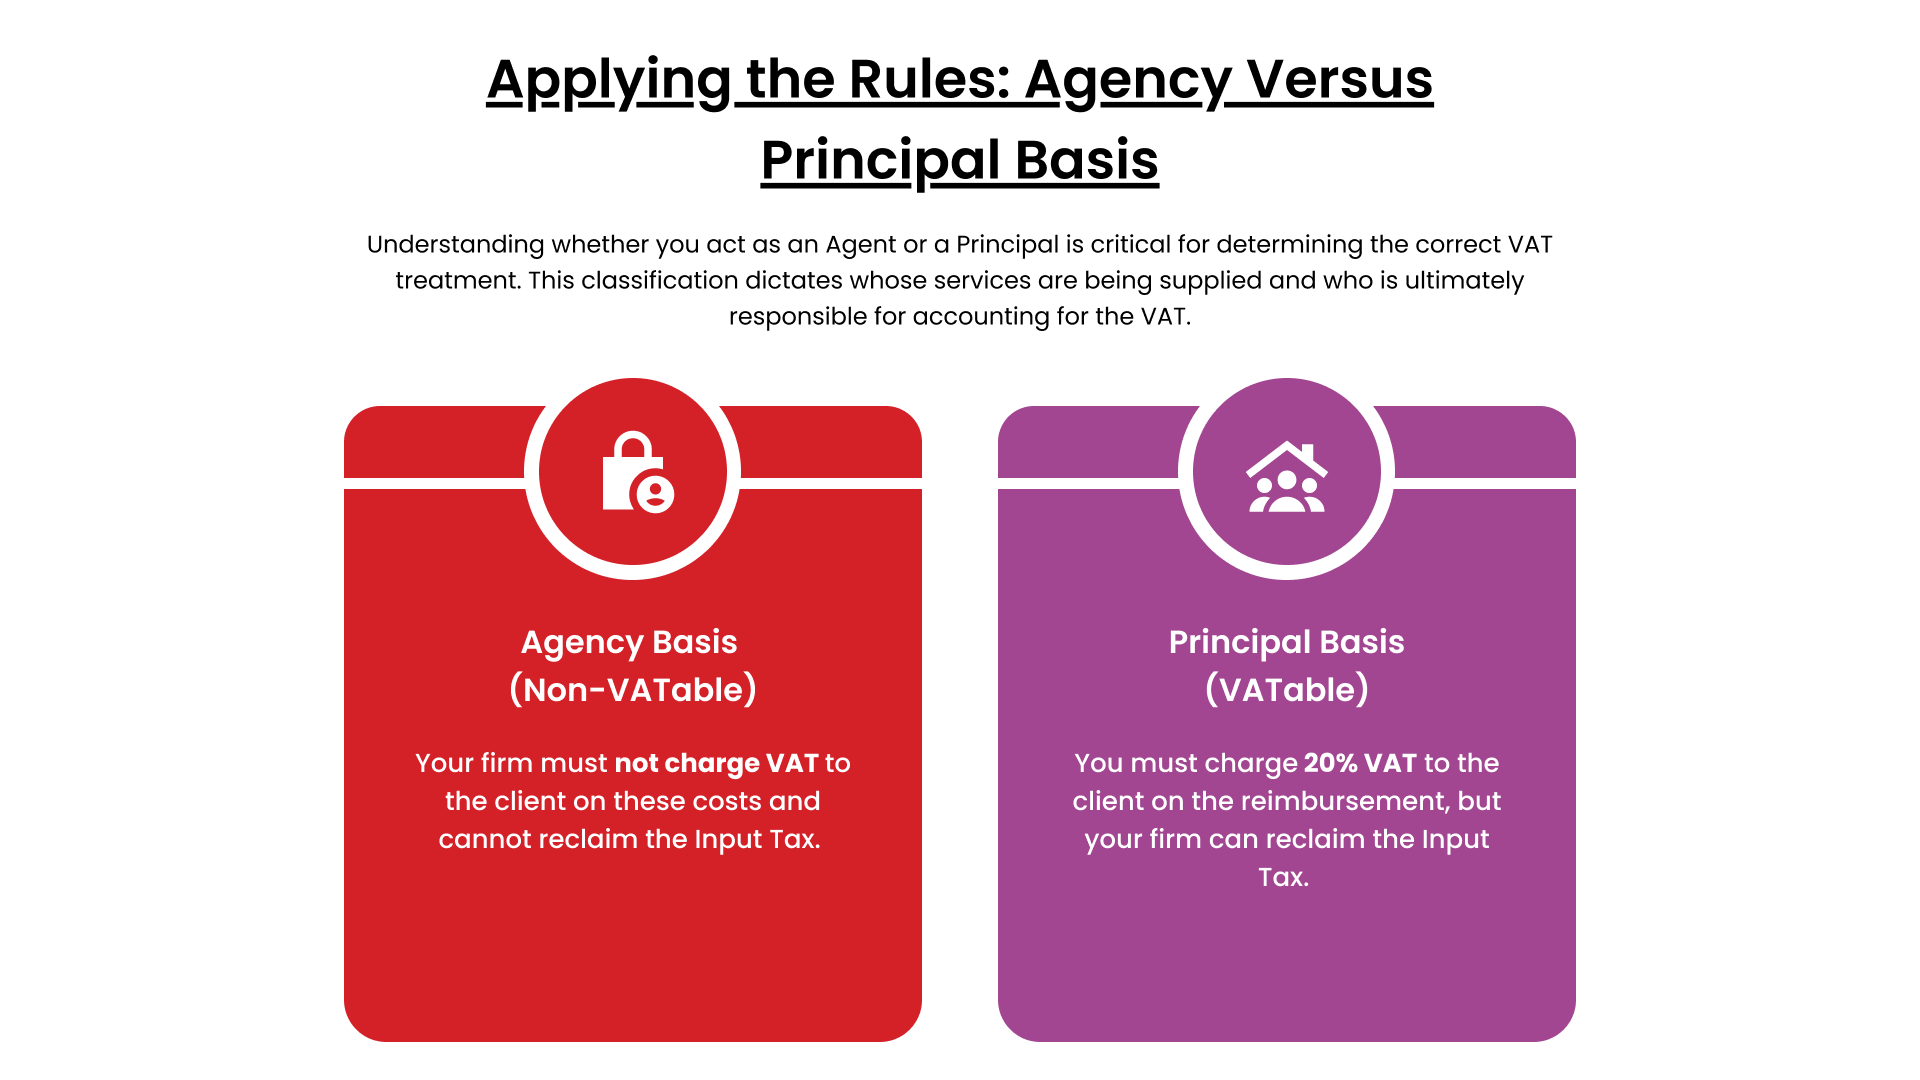
Under the Agency Basis, your firm acts purely as a financial agent. The supply is made to and consumed by the client.
The Key Test: The goods or services are ordered by the solicitor but are used or consumed by the client. The solicitor simply facilitates the payment.
VAT Treatment: Your firm must not charge VAT to the client on these costs.
Input Tax: Your firm cannot reclaim the Input Tax because the supply was not made to you.
AZL Value: Our AZL accountants verify that your client retainer agreements accurately reflect the true Agency relationship, securing your non-VATable costs.
Essential Examples of True Agency Disbursements (Non-VATable):
Court Fees (charged by HM Courts & Tribunals Service)
Land Registry Fees
Counsel’s Fees (fees for a barrister or external advocate supplied directly to the client)
Expert Witness Fees
The Principal Basis: Costs Supplied to the Firm (VATable)
Under the Principal Basis, your firm consumes the goods or services as part of its own process to deliver the overall legal service. The supply is made to the law firm. You then incorporate this cost into the total charge for the legal service.
The Key Test: The cost is an overhead of your firm, even if attributable to a specific case. The solicitor consumes the service.
VAT Treatment: You must charge Standard Rate VAT (20%) to the client on the reimbursement of this cost, as it forms part of your total taxable supply.
AZL Value: We ensure your internal billing systems correctly apply the 20% VAT to all Principal costs, protecting your firm from under-collection risk.
Essential Examples of Principal Disbursements (VATable):
Travel costs (e.g., solicitor’s train fare or mileage for a hearing)
Photocopying and internal printing charges
General administrative overheads (e.g., bulk postage or telephone charges)
Legal search fees that are essential for the solicitor’s own research
Input Tax Recovery: Reclaiming VAT Paid on Principal Costs
Since costs under the Principal Basis are supplied to your firm, you possess the legal right to recover the Input Tax paid to the supplier.
AZL ensures your firm correctly identifies these recoverable costs, distinguishing them from Agency costs.
We actively prevent the erroneous reclamation of VAT on Agency Disbursements, which is a common and high-risk audit trap. Our robust approach safeguards your recoverable Input Tax claims.
Operational Requirements: Intersections with Financial Conduct Rules
VAT obligations directly intersect with core professional responsibilities, particularly the Solicitors Accounts Rules (SAR) mandated by the Solicitors Regulation Authority (SRA).
SAR Compliance: Managing Client Money and the VAT Liability
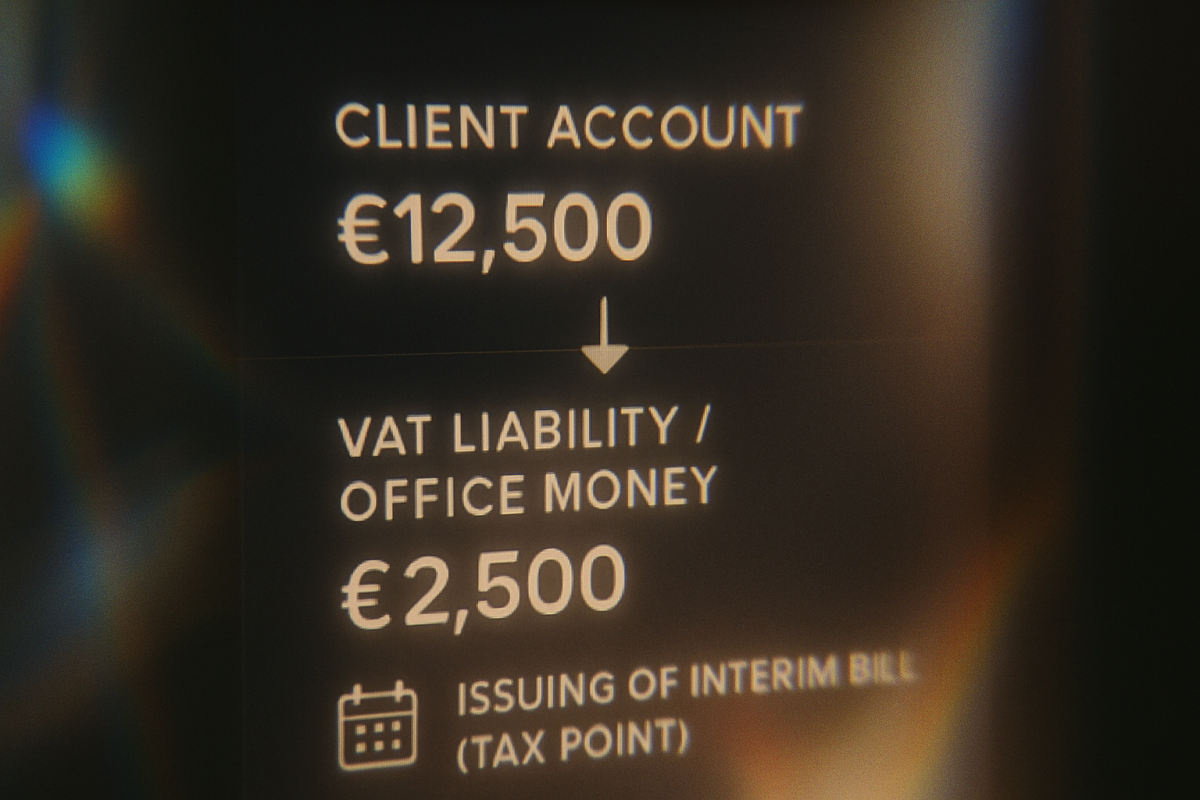
Legal Jargon:Office Money and Client Money. The VAT element of your fees is strictly classified as Office Money (money belonging to the firm/HMRC), not Client Money. The firm must maintain this distinction.
Interim Bills establish a Tax Point, meaning the VAT portion becomes due to HMRC immediately, even if the client has not paid the full amount.
AZL accountants stress that firms must correctly calculate and separate the VAT portion before transferring funds from the Client Account to the Office Account.
Accurate VAT accounting is vital for maintaining SAR compliance and avoiding professional conduct breaches, ensuring the SRA does not flag your practices.
International Clients: Applying the Place of Supply Rules
Firms advising international clients must rigorously apply the Place of Supply Rules.
For B2B legal services, the place of supply is generally where the client is established.
This can result in the service being Outside the Scope of UK VAT for overseas clients, meaning no UK VAT is charged.
Applying these rules incorrectly leads to either overcharging the client or failing to meet HMRC’s zero-rating requirements. AZL Accountants provides the specialist billing expertise to navigate this complex area correctly.
Accounting Methods: Accrual vs. Cash Accounting for VAT Reporting
Your firm’s choice of accounting method dictates your VAT filing obligations and cash flow.
Accounting Method
VAT Liability Trigger
Availability
AZL’s Role
Standard Accrual
Invoice Date (Tax Point)
Mandatory for larger firms.
Ensures accurate tracking of invoices and timely liability reporting.
Cash Accounting
Payment Date
Restricted to smaller firms meeting HMRC turnover limits.
Advises if your firm qualifies and manages the transition to optimise cash flow.
AZL Assurance: Securing Your Firm’s VAT Position in England and Wales
As specialist accountants for the legal sector, AZL understands the regulatory environment in which you operate. Our expertise supports your entire financial framework, securing your reputation and profitability.
Proactive Compliance Reviews: Auditing Current Billing Systems
Our expert accountants proactively audit your current fee agreements and invoicing systems.
We benchmark your practices against published HMRC guidelines and relevant UK case law, using our detailed knowledge to flag and eliminate any risk areas, such as misclassified Principal or Agency disbursements.
This proactive approach minimises your exposure to future HMRC interventions.
Specialist Guidance: Training Fee-Earners and Administrative Staff
We provide clear, practical training and establish internal documented policies for your staff, ensuring a consistent and correct application of VAT rules firm wide.
How AZL Accountants Eliminates the Risk of Output Tax Errors
We assure your firm correctly calculates and charges the Output Tax (VAT on services) every time. Our rigorous internal controls significantly minimise the risk of HMRC assessment and penalties due to incorrect categorisation, providing partners with essential assurance.
Connect with AZL Accountants for a confidential Billing Compliance Consultation and fortify your practice against HMRC scrutiny across England and Wales.
Law firm partners and practice managers across England and Wales face constant regulatory pressure. Managing Value Added Tax (VAT) correctly, especially regarding client fees and the accurate definition of a disbursement presents a major financial and regulatory exposure. Misclassification on an invoice...
Unidentified funds entering your legal firm’s accounts create an immediate regulatory and financial risk. In the highly regulated environment of England and Wales, where Solicitors Regulation Authority (SRA) Accounts Rules govern every transaction, a simple bank receipt with an unknown source can jeopardise your Trial Balance and compliance standing. Law firms require an...
For law firm partners and practice managers in England and Wales, managing client finances securely and compliantly presents a persistent, high-stakes challenge. The integrity of your firm hinges on impeccable financial record-keeping. You need clarity and confidence in every transaction, ensuring you satisfy the rigorous demands of the Solicitors Regulation Authority (SRA) while maintaining profitable operations. AZL Accountants provides the specialist expertise your firm needs....


 3 July 2026
 1 July 2026