Post-Brexit, determining VAT on cross-border legal services is governed by the complex Place of Supply (PoS) rules, escalating compliance risk if your procedures are incorrect. The penalties for misclassifying a transaction especially those involving the Reverse Charge are often severe and retroactive.
Our expert accountants at AZL resolves this uncertainty. We provide definitive guidance on HMRC requirements for services supplied to the EU and the Rest of the World (ROW), ensuring you execute the correct VAT treatment every time. Partner with AZL to safeguard your international fee income and eliminate audit exposure.
Foundation First: Mastering the UK VAT Framework Post-Brexit
The key to compliant cross-border billing is establishing the Place of Supply (PoS). This single determination dictates whether you charge UK VAT, zero-rate the supply, or treat it as outside the scope of UK tax.
Defining Place of Supply (PoS) for Legal Services
For most legal services, the rules are simplified based on the client’s status: Business to Business (B2B) or Business to Consumer (B2C). Legal services fall under the General Rule, but proving the client status is mandatory.
Client Status
PoS General Rule
UK VAT Charged by Supplier?
B2B (Business to Business)
Where the customer belongs (Location of Recipient).
No (Customer Reverse Charges).
B2C (Business to Consumer)
Where the supplier belongs (Location of Supplier/UK).
Yes (UK Standard Rate, 20%).
AZL Assurance: Proving the customer’s B2B status is mandatory for applying the Reverse Charge. If proof is insufficient, HMRC may compel you to charge UK VAT retrospectively, creating a retrospective liability for your firm.
Critical VAT Jargon Explained
Using the wrong terminology internally or on an invoice is a primary trigger for incorrect filing. AZL’s accountants clarify the essential terms required for international billing accuracy:
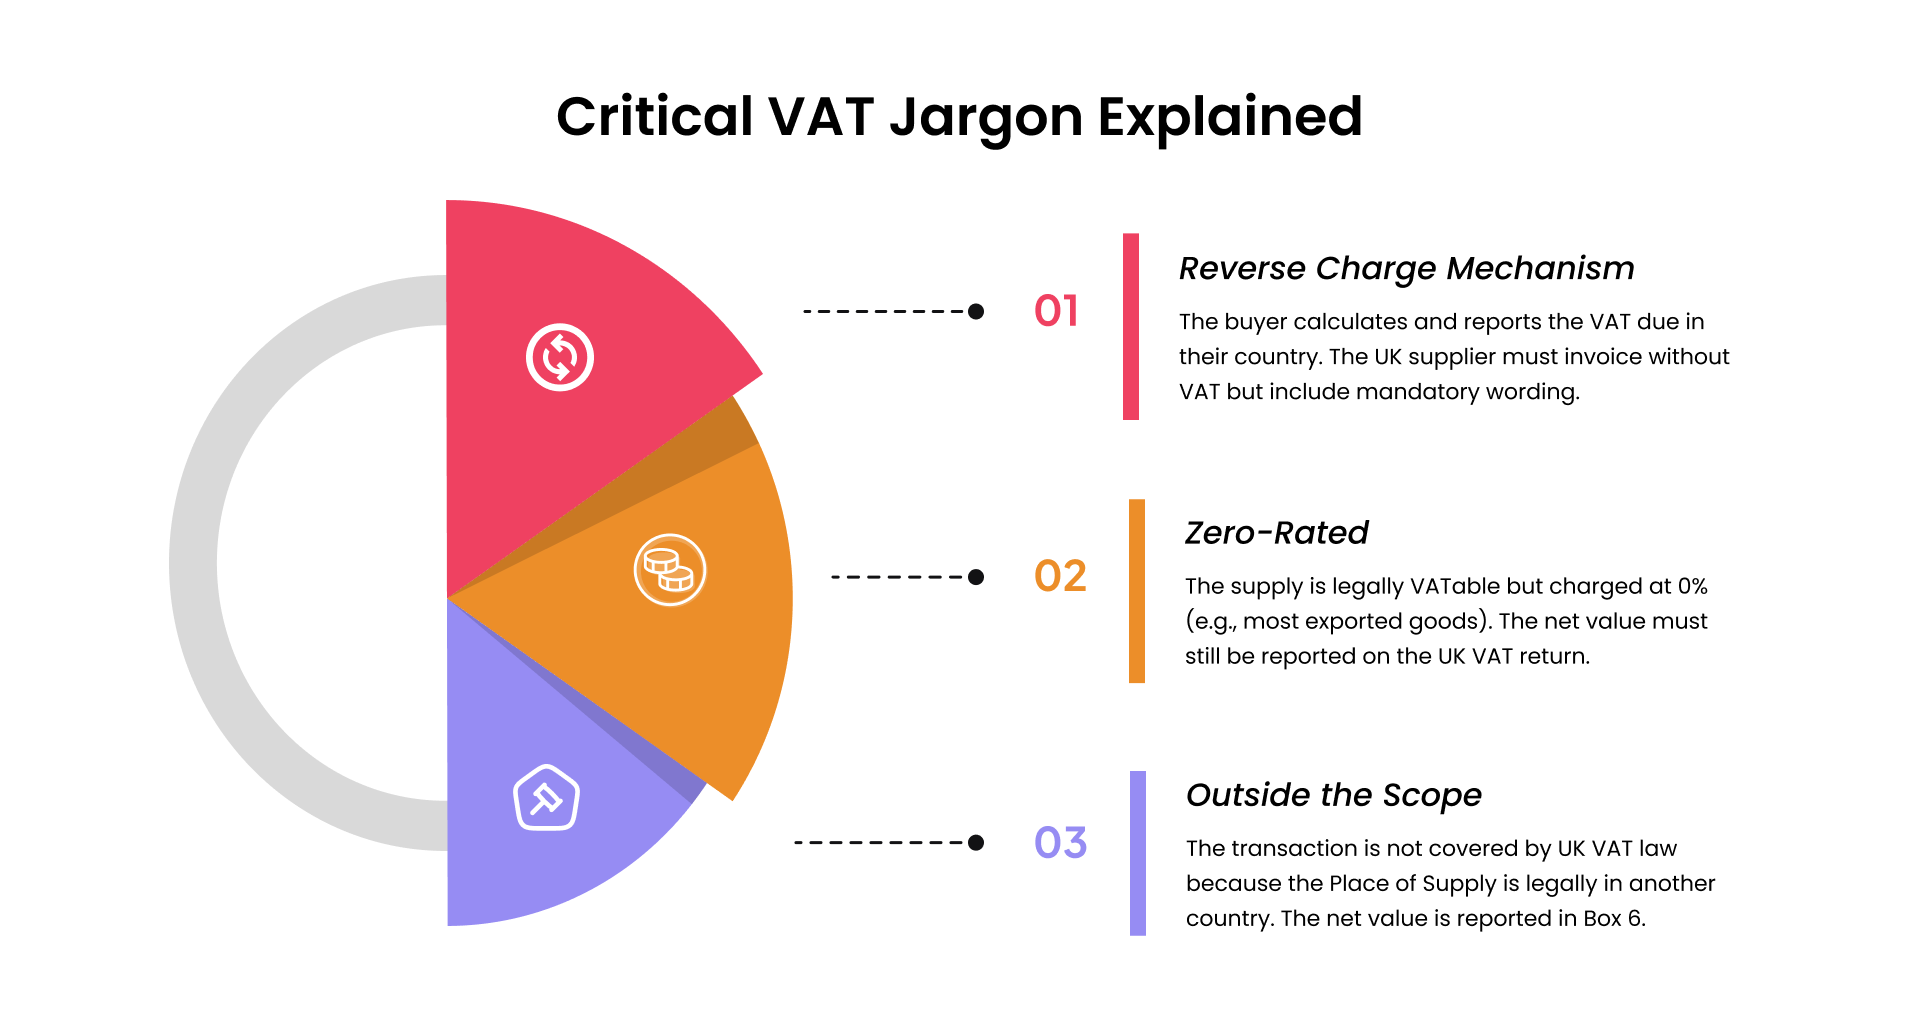
Reverse Charge Mechanism: The buyer, not the seller, is responsible for calculating and reporting the VAT due in their country. The UK supplier invoices without VAT but includes mandatory wording.
Zero-Rated: The supply is legally VATable, but the rate is 0% (e.g., most exported goods). The net value is still reported on the UK VAT return.
Outside the Scope: The transaction is not covered by UK VAT law because the PoS is legally another country. It is essentially non-VATable from a UK perspective, but the value is still reported in Box 6.
AZL’s Role in Interpreting Complex HMRC Guidance
HMRC’s guidance (specifically VAT Notice 741A) contains nuanced exceptions that frequently catch out law firms. AZL specialises in translating this complexity into actionable, auditable billing procedures.
We minimise misclassification penalties by:
Pinpointing Exceptions: Identifying when the General Rule is overridden by a specific exception (e.g., land-related services or Intellectual Property rights).
Enforcing Controls: Implementing internal checks to ensure all Reverse Charge conditions are met before the invoice is sent.
EU Clients: VAT Treatment of Services to EU Clients
Post-Brexit, services supplied from the UK to the EU (excluding Northern Ireland) follow the same rules as those supplied to the Rest of the World (ROW). The key to compliant billing is accurately identifying the client.
B2B Services Supplied to EU VAT-Registered Clients
This is the most common scenario. If the customer is a business, the General Rule applies, simplifying your billing but heightening your need for documentation.
Applying the General Rule: The Place of Supply is the EU client’s location. The UK law firm (supplier) invoices at 0% VAT, and the EU client must account for the VAT via the Reverse Charge mechanism in their country.
Enforcing Proof of Status: You must obtain and validate the client’s EU VAT Identification Number (VIES check is highly recommended). Lack of proper EU VAT registration proof means HMRC can enforce retrospective UK VAT charges.
B2C Services Supplied to EU Private Individuals
When a UK law firm supplies general services to an EU private individual, the default is to charge UK VAT, as the PoS is the supplier’s location.
The Default Rule: The Place of Supply is the UK (where the supplier belongs). You must apply the UK standard-rate of VAT (currently 20%).
Key Exceptions to the General Rule (AZL Specialisation):
Land-Related Services: If the legal service relates directly to immovable property in the EU (e.g., conveyance, litigation over EU property), the PoS is where the land is located. This requires local VAT registration or specific local advice.
Transport or Cultural Services: Specific services, such as those relating to transport or cultural events, have separate PoS rules that override the B2C general rule.
Global Trade: VAT Treatment of Services to ROW Clients
For clients located in the Rest of the World (ROW) e.g., the US, Asia, Africa—the rules are simpler, following the same principles as the EU post-Brexit.
B2B Services Supplied to Rest of World (ROW) Businesses
The General Rule for B2B supplies simplifies trade with non-EU jurisdictions.
Treatment: The Place of Supply is deemed to be outside the UK. The supply is outside the scope of UK VAT (or zero-rated if the customer is a business).
Documentation Requirements:
AZL mandates robust documentation to prove the client’s business status and location to HMRC during an audit:
Dated contracts and detailed letters of engagement.
Company registration details from the client’s jurisdiction.
Clear, verifiable business addresses.
B2C Services Supplied to Rest of World (ROW) Consumers
For general B2C services, the supply is typically treated as outside the UK’s tax jurisdiction, meaning you do not charge UK VAT.
Outside the Scope Treatment: When the service is supplied to an ROW consumer, it remains outside the scope of UK VAT (under the General Rule). No UK VAT is charged.
Compliance Rigour: Reporting Requirements for UK Law Firms
Correctly determining the Place of Supply is only half the battle. Your UK VAT return must accurately reflect all international transactions to satisfy HMRC’s stringent audit requirements.
Accounting for Cross-Border VAT on the UK VAT Return
Cross-border supplies must be accurately recorded in the correct boxes of the VAT return. Correct use of Box 6 (Total Net Sales) and Box 7 (Total Net Purchases) is crucial.
Transaction Type
Box 1 (Output VAT Due)
Box 6 (Total Net Sales Value)
Box 7 (Total Net Purchase Value)
B2B Services Supplied Abroad (Reverse Charge)
£0
Include Net Value of Service
£0
B2B Services Received (Reverse Charge)
Include Output VAT Due
Include Net Value (Deemed Supply)
Include Net Value (Actual Purchase)
B2C Services Supplied in ROW (Outside Scope)
£0
Include Net Value of Service
£0
The Requirement for Accurate Invoicing and Records
Your invoice is the primary audit trail for any international fee. Inaccurate or incomplete wording is a primary trigger for HMRC investigations.
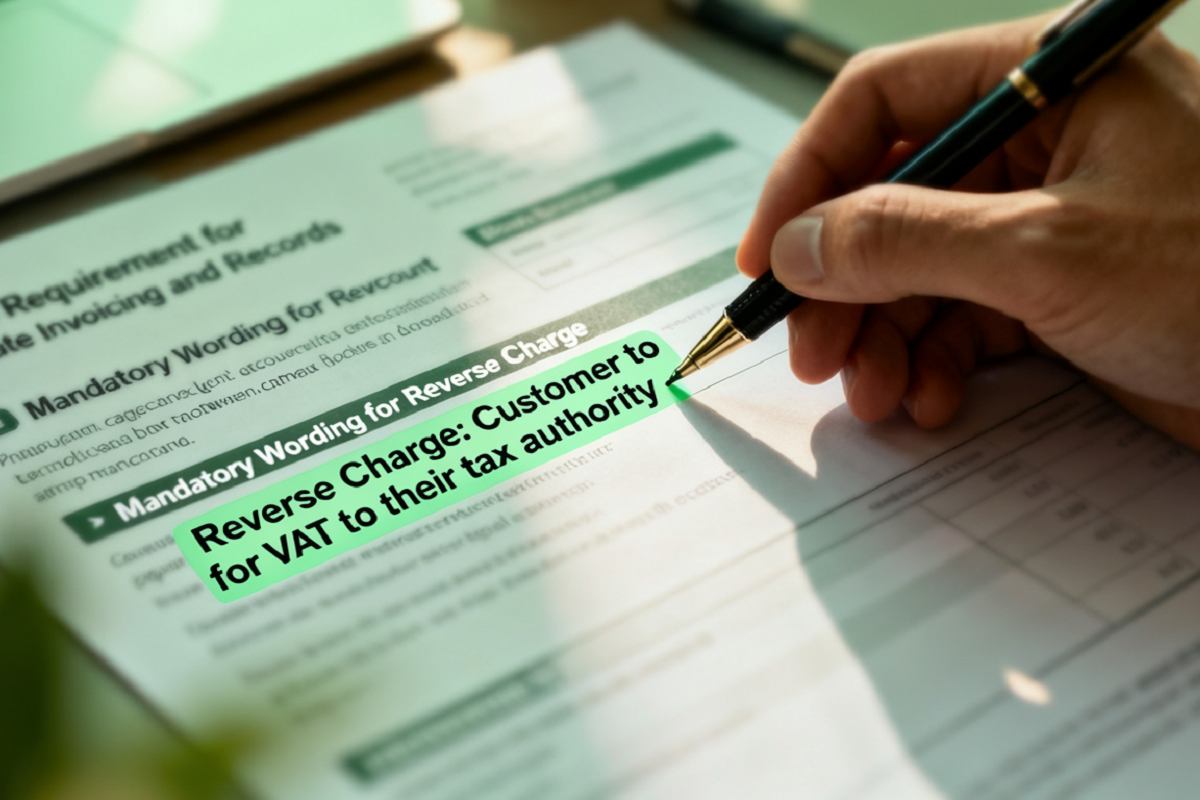
Mandatory Wording for Reverse Charge: Invoices for Reverse Charge supplies must not include UK VAT, and must contain a clear, explicit statement under UK law:
“Reverse Charge: Customer to account for VAT to their tax authority.”
Record-Keeping Obligations: AZL helps establish stringent record-keeping protocols under HMRC requirements for proving the client’s location and business status (e.g., VIES validation checks, dated contracts, clear business addresses).
Law firm partners and practice managers across England and Wales face constant regulatory pressure. Managing Value Added Tax (VAT) correctly, especially regarding client fees and the accurate definition of a disbursement presents a major financial and regulatory exposure. Misclassification on an invoice...
Unidentified funds entering your legal firm’s accounts create an immediate regulatory and financial risk. In the highly regulated environment of England and Wales, where Solicitors Regulation Authority (SRA) Accounts Rules govern every transaction, a simple bank receipt with an unknown source can jeopardise your Trial Balance and compliance standing. Law firms require an...
For law firm partners and practice managers in England and Wales, managing client finances securely and compliantly presents a persistent, high-stakes challenge. The integrity of your firm hinges on impeccable financial record-keeping. You need clarity and confidence in every transaction, ensuring you satisfy the rigorous demands of the Solicitors Regulation Authority (SRA) while maintaining profitable operations. AZL Accountants provides the specialist expertise your firm needs....


 3 July 2026
 1 July 2026