For senior lawyers, a sabbatical or career break offers an invaluable chance to refocus. However, for high-net-worth individuals, this transition presents complex tax challenges that generic accounting cannot solve. Without specialist guidance, an extended leave can inadvertently trigger substantial, unforeseen tax liabilities under HMRC rules.
At AZL, our expert accountants fortify your financial position across England and Wales. We provide the essential clarity you need to navigate UK tax law, ensuring your break is financially rewarding, not costly. We protect your wealth and convert potential tax risks into clear, strategic financial advantages.
Distinguishing Your Break: Tax Definitions and Payment Structures
The tax implications of your break hinge entirely on your employment status during the period. UK tax law rigidly distinguishes between a true sabbatical and a formal career break, dictating exactly how your final payments are processed and taxed. AZL ensures your agreement aligns with tax best practice.
The Contract Status: Suspension vs. Termination
You must first establish the formal agreement with your firm. This status fundamentally determines your ongoing rights, benefits, and tax reporting requirements under PAYE (Pay As You Earn).
Contract Status
Legal Definition
Core Tax Impact
Sabbatical (Contract Suspension)
The employment contract remains in force or is formally suspended. You retain continuity of service.
Your existing PAYE tax code continues, often leading to overpayment of tax because the system assumes full annual earnings.
Career Break (Contract Termination)
The contract of employment is formally severed or terminated.
Payments received upon termination may legally qualify for the powerful £30,000 tax exemption.
AZL accountants strategise with you and your firm to ensure the payment terms align precisely with HMRC rules, securing the best possible outcome for your personal finances.
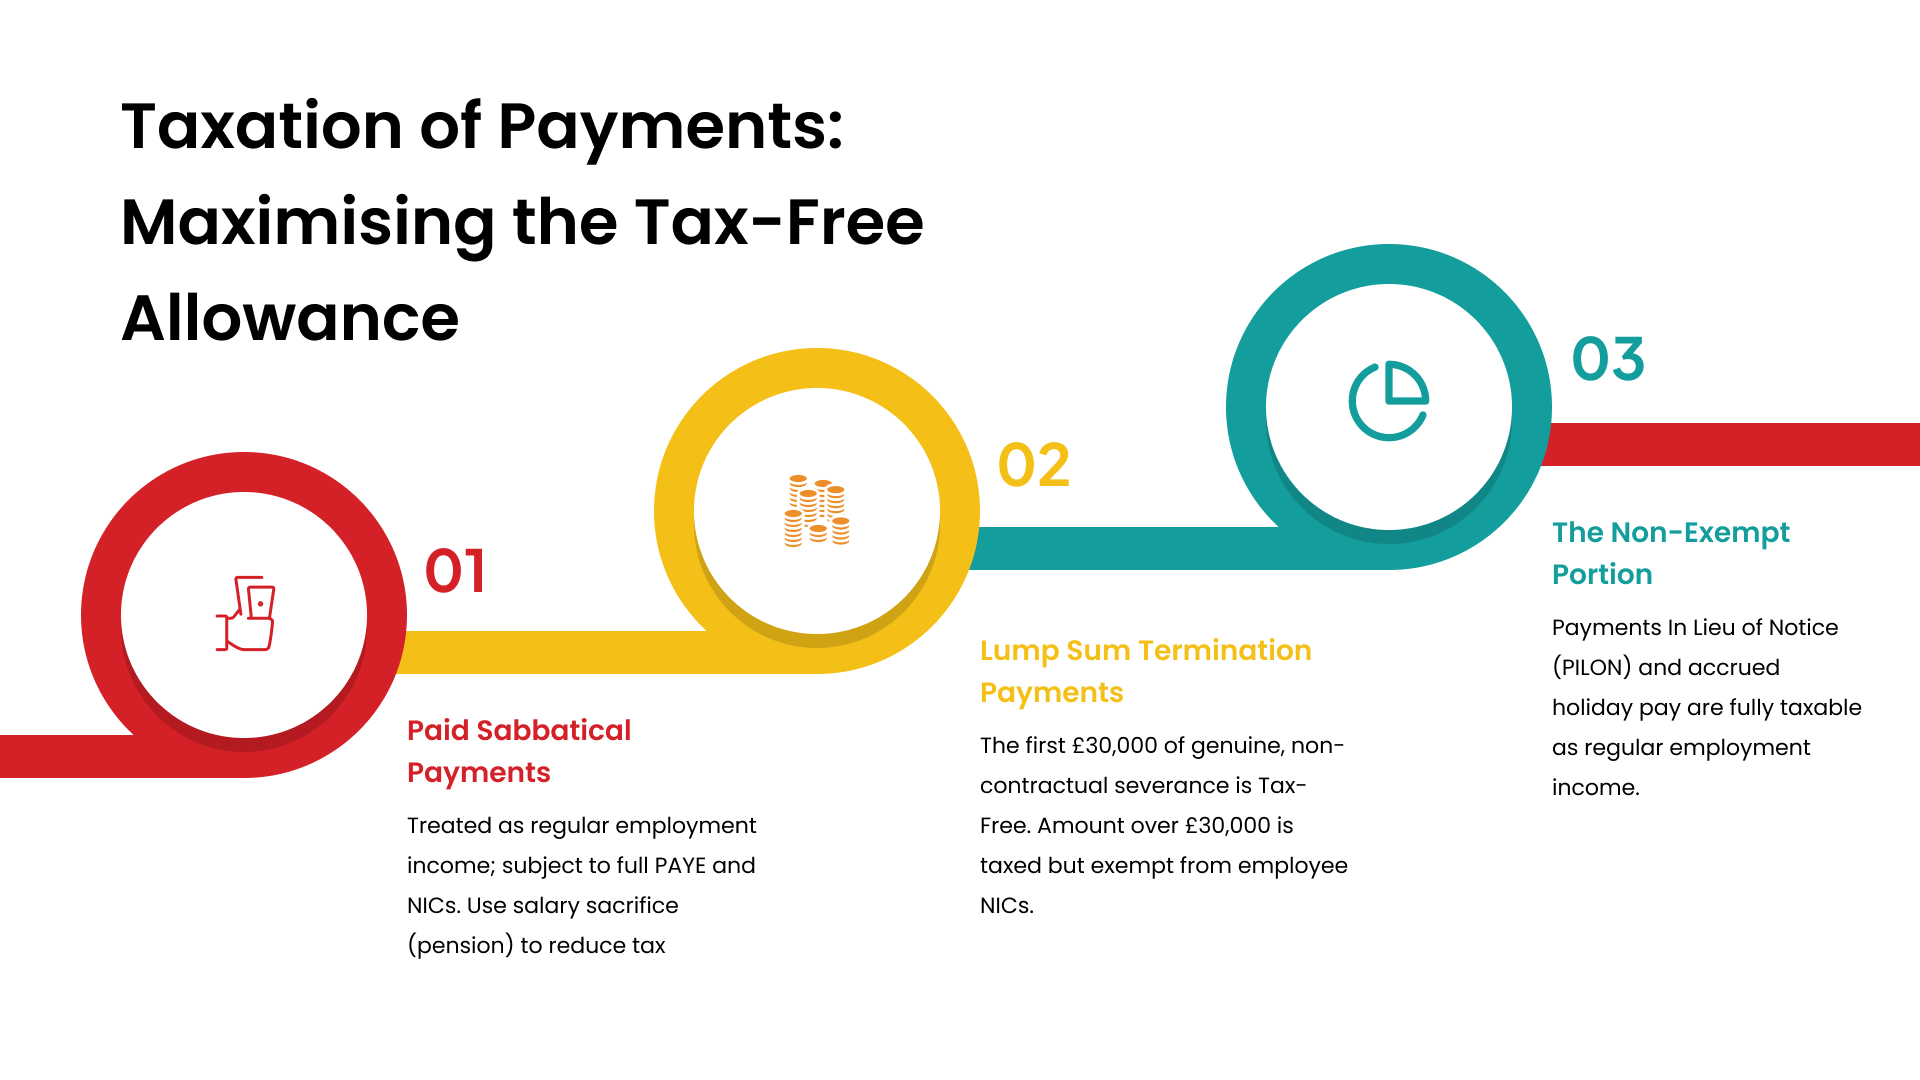
Taxation of Payments: Maximising the Tax-Free Allowance
How your firm classifies any final lump sum payments is critically important. Our expertise helps you legally differentiate between standard taxable salary and the potentially tax-exempt portion.
Paid Sabbatical Payments:
Any paid leave is treated as regular employment income. It is subject to full PAYE and NICs (National Insurance Contributions).
AZL Action: We recommend using salary sacrifice for pension contributions before the break begins. This action utilises high-earner relief to immediately reduce your taxable income base for the year.
Lump Sum Termination Payments:
The £30,000 Exemption: The first £30,000 of a genuine non-contractual, ex-gratia termination payment is tax-free. The amount exceeding £30,000 is subject to Income Tax but is exempt from employee NICs.
The Non-Exempt Portion: Payments In Lieu of Notice (PILON) and accrued holiday pay are fully taxable as regular employment income.
We verify the classification of every pound you receive to ensure the full £30,000 exemption is correctly applied to the eligible component, protecting you from future HMRC challenges and penalties.
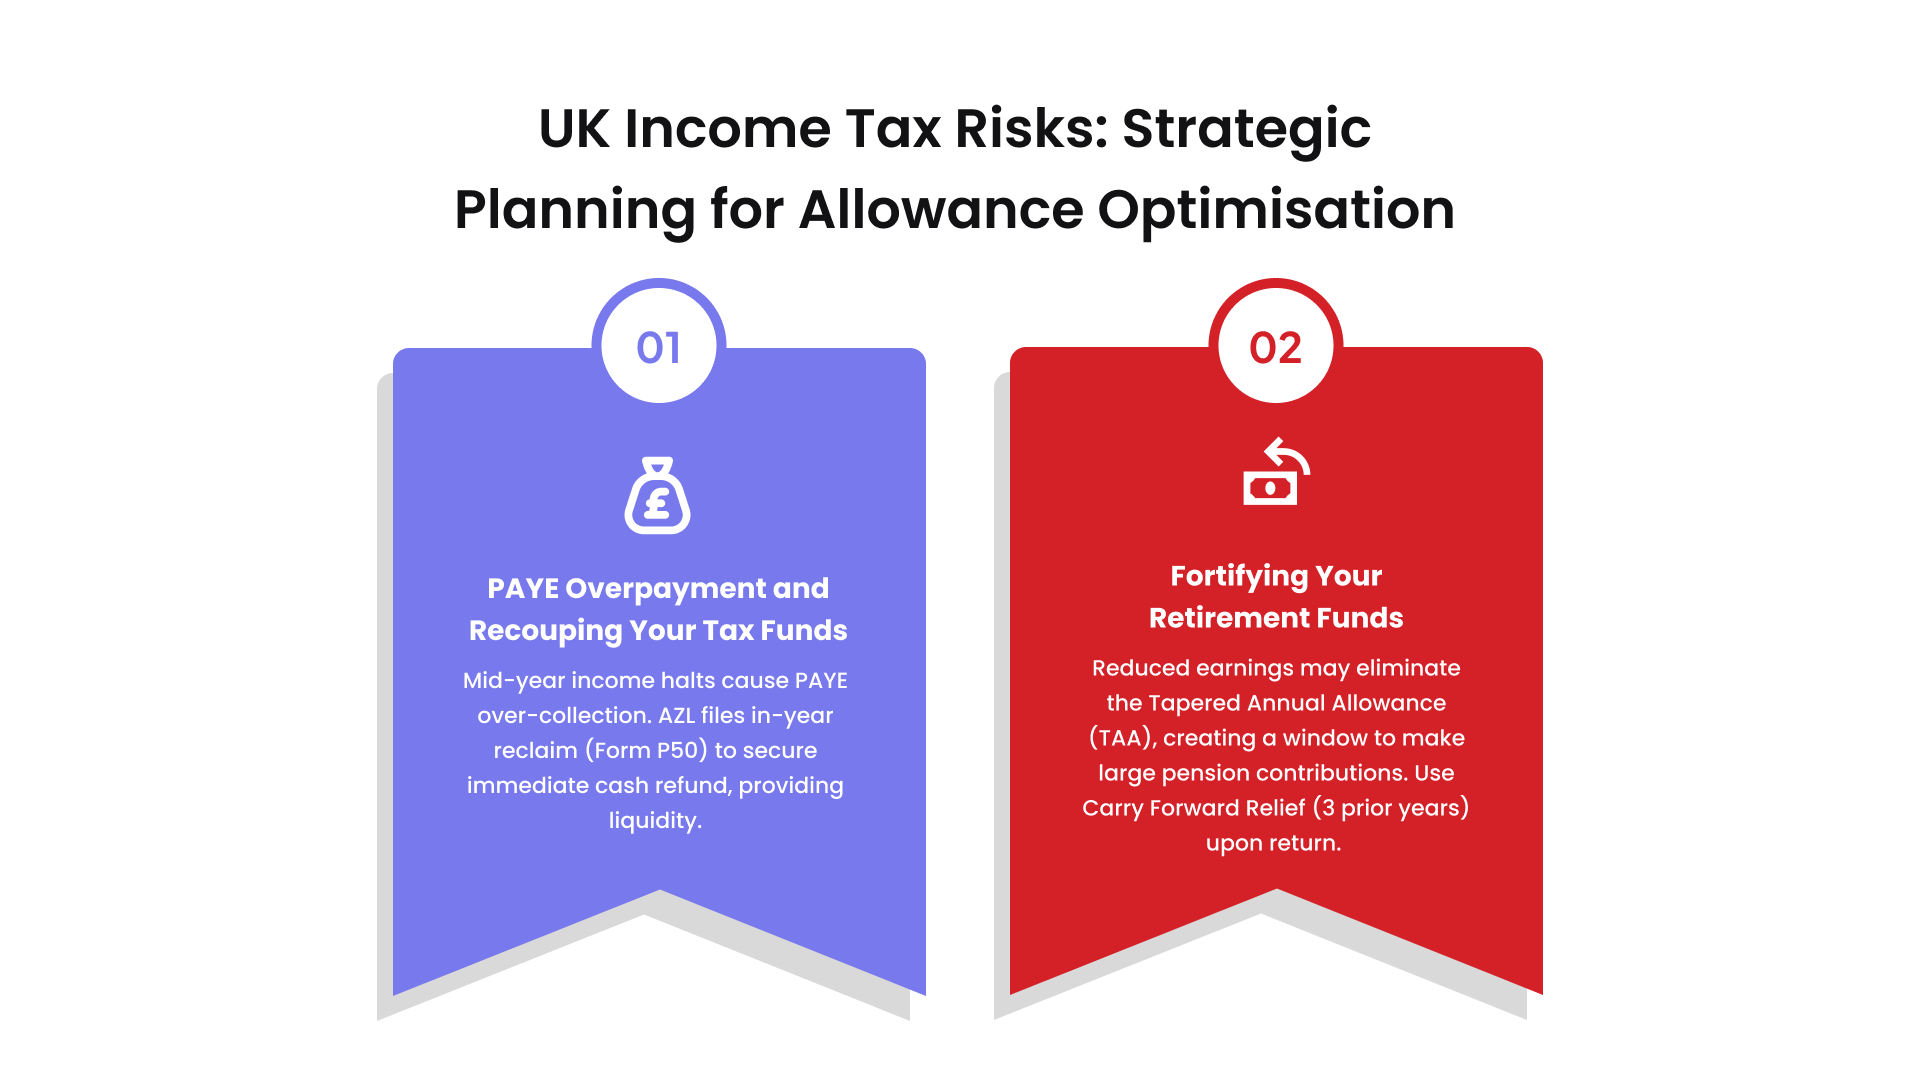
UK Income Tax Risks: Strategic Planning for Allowance Optimisation
A halt in salary mid-year creates immediate financial disruptions that high earners must proactively address. AZL transforms this period of zero income into a strategic tax planning opportunity.
PAYE Overpayment and Recouping Your Tax Funds
Because the UK tax system is structured for consistency, stopping income mid-year always causes the PAYE system to over-collect tax, as it assumes you will earn your monthly salary for the entire tax year (6 April to 5 April).
The Overpayment Mechanism: This cumulative tax deduction becomes excessive, resulting in a substantial overpayment of tax to HMRC.
Maximising Your Personal Allowance: Your Personal Allowance (currently £12,570 for 2025/26) must be fully utilised. When income drops, we ensure this allowance is not wasted.
The AZL Solution: Accelerating Your Refund
Waiting for the standard P800 process after the tax year ends can mean waiting months for your cash.
AZL accountants manage the in-year tax reclaim process for you, typically using Form P50.
We secure the immediate refund of the tax you have overpaid, providing essential liquidity during your sabbatical.
Pension Strategies: Fortifying Your Retirement Funds
For senior lawyers, the Tapered Annual Allowance (TAA) presents complex planning concerns and unexpected opportunities that require specialist modelling.
The Loss of Contributions: You immediately lose valuable employer contributions to your Registered Pension Schemes during unpaid leave.
Leveraging the Tapered Annual Allowance (TAA):
The TAA significantly restricts the maximum annual pension contribution for high earners. Tapering begins when Adjusted Income exceeds £260,000.
A period of reduced or zero earnings during a career break means your Adjusted Income can drop dramatically, potentially eliminating the TAA restriction entirely for that tax year.
Strategic Advantage: This creates a valuable window to make significant pension contributions without triggering the TAA, a key financial planning tool.
Utilising Carry Forward Relief:
You can utilise unused Annual Allowance from the three preceding tax years (Carry Forward).
AZL accountants precisely calculate your unused allowance, helping you execute a major top-up contribution upon your return to work, further fortifying your retirement savings.
Do not risk an HMRC investigation or a surprise tax bill. Contact AZL now to schedule your specialised pre-break tax consultation.
Residency and Capital Taxes: Mitigating Risk on Longer Breaks
For senior lawyers planning a longer break involving temporary relocation overseas, the risk profile shifts dramatically. The central challenge is avoiding unintended UK tax liabilities on worldwide assets.
Mastering the Statutory Residence Test (SRT)
If your absence spans a full UK tax year, you must understand the Statutory Residence Test (SRT)—HMRC’s definitive rule set for determining your UK tax status.
The SRT’s Authority: The SRT dictates whether you are liable for UK tax on your worldwide income and gains.
Risk of Inadvertent Residency: Even short returns to the UK can unintentionally trigger residency based on “sufficient ties” (family, available accommodation, etc.).
The Critical Rule: Spending 183 days or more in the UK automatically makes you resident for the year.
Split-Year Treatment: AZL helps you apply for Split-Year Treatment, treating your tax year as two distinct periods: one UK resident, one non-UK resident. This limits your UK tax liability to UK-sourced income for the overseas period.
Managing Property and Capital Gains Tax (CGT)
Extended breaks carry specific risks related to asset disposals, particularly the family home.
CGT on UK Property: Your liability for UK CGT on the sale of UK residential property remains, regardless of temporary non-residency.
Preserving PPR Relief: Extended non-occupancy periods can potentially erodePrincipal Private Residence (PPR) relief on your main home. We calculate and advise on deemed occupancy periods to preserve the maximum PPR exemption possible upon sale, protecting a potentially six-figure tax relief.
Inheritance Tax (IHT) and Domicile
Senior professionals must ensure their existing estate planning remains robust during a break, as IHT liability is governed by fundamental concepts.
Domicile Governs IHT: IHT liability is primarily governed by your domicile (the place you consider your permanent home). A short sabbatical does not alter your Domicile of Origin or Domicile of Choice.
Worldwide Assets: As a UK-domiciled individual, your worldwide assets remain potentially subject to IHT on death. AZL provides integrated IHT advisory to ensure your sabbatical planning aligns with your broader generational wealth strategy.
Partnering with AZL: Your Pre-Break Tax Security Strategists
Your time away from the firm should be rejuvenated, not consumed by HMRC compliance risks. AZL serves as your dedicated specialist advisor, actively securing your financial position and ensuring total compliance.
We offer integrated, proactive solutions that transform complex UK tax rules into clear, actionable planning points.
AZL Service Action
Key Financial Benefit
Pre-Sabbatical Tax Review
Reviews your contract and payment structure to ensure maximum tax efficiency.
Lump Sum Optimisation
Verifies eligibility and secures the full £30,000 tax exemption for termination payments.
Residency and Travel Modelling
Determines the precise maximum number of UK days allowable under the SRT, providing a clear travel plan.
Pension Contribution Strategy
Models your Tapered Annual Allowance status to fortify your retirement savings using Carry Forward relief.
Ongoing Compliance and Seamless Financial Transition
Our support does not end when you leave. We guarantee that your return to the firm is financially seamless and fully compliant.
We manage your annual Self-Assessment filing, ensuring all complex tax reliefs and in-year refunds of overpaid PAYE are correctly claimed by HMRC.
We reconcile any overseas income using the correct double taxation relief rules, preventing you from paying tax twice on the same earnings.
We deliver the financial peace of mind you deserve, allowing you to focus completely on your break.
Protect Your Financial Freedom with AZL
A sabbatical is an investment in yourself. Do not allow complex tax rules to diminish its value. The specialist rules governing employment breaks, lump sum payments, and residency require the precise, authoritative expertise that only AZL provides.
Take Control of Your Transition
AZL’s expert accountants act as your financial security strategists, protecting your high-net-worth status throughout your time away and ensuring total compliance with HMRC regulations in England and Wales.
Take the crucial step to secure your financial freedom. Contact AZL now to schedule your specialised pre-sabbatical tax strategy consultation. Let our expertise convert your tax uncertainties into robust financial certainty.
Law firm partners and practice managers across England and Wales face constant regulatory pressure. Managing Value Added Tax (VAT) correctly, especially regarding client fees and the accurate definition of a disbursement presents a major financial and regulatory exposure. Misclassification on an invoice...
Unidentified funds entering your legal firm’s accounts create an immediate regulatory and financial risk. In the highly regulated environment of England and Wales, where Solicitors Regulation Authority (SRA) Accounts Rules govern every transaction, a simple bank receipt with an unknown source can jeopardise your Trial Balance and compliance standing. Law firms require an...
For law firm partners and practice managers in England and Wales, managing client finances securely and compliantly presents a persistent, high-stakes challenge. The integrity of your firm hinges on impeccable financial record-keeping. You need clarity and confidence in every transaction, ensuring you satisfy the rigorous demands of the Solicitors Regulation Authority (SRA) while maintaining profitable operations. AZL Accountants provides the specialist expertise your firm needs....



 3 July 2026
 1 July 2026